A geothermal power plant makes electricity by pulling heat from underground water or steam and using it to spin a turbine, and a site’s fluid temperature decides which of three plant designs it needs, with 182°C, or 360°F as the cutoff. That heat sits under almost every patch of ground on earth, but geothermal still meets less than 1% of world energy demand because most hot rock lacks the permeability a plant needs to move water through it.
Enhanced geothermal systems, or EGS, force that missing permeability into the rock instead of waiting to find it. Fervo Energy’s Cape Station in Beaver County, Utah showed the approach can run at commercial scale, reaching first power in September 2026.
Three ways to turn underground heat into power
There are three commercial designs, and a site’s resource temperature decides which one it uses.
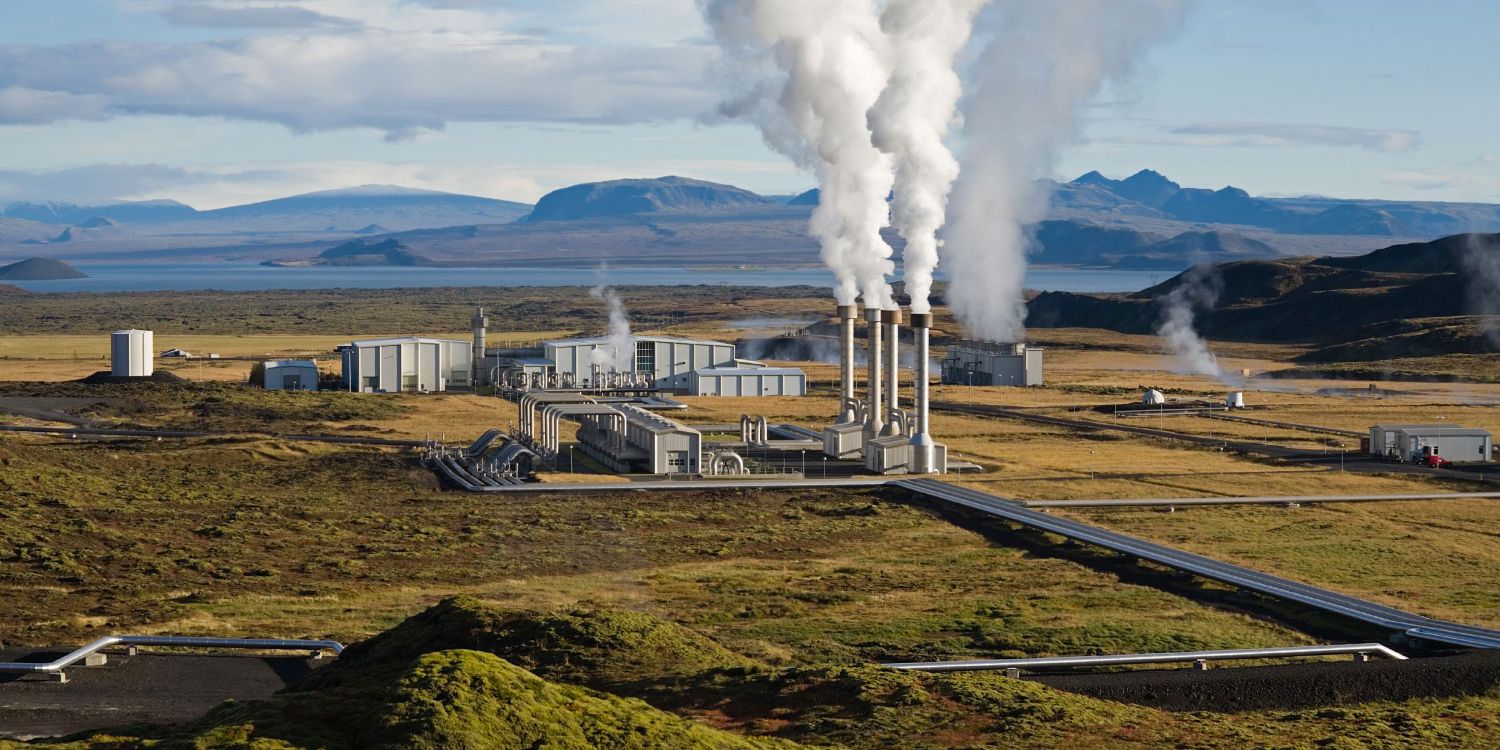
Dry steam plants are the simplest design. The underground reservoir already produces steam instead of hot water, so that steam runs straight to the turbine, the way a kettle’s whistle can spin a fan held over the spout. The Geysers in Northern California is the world’s largest single source of geothermal power, a design first proven in Italy in 1904 and still running there. If your utility buys power from Northern California, there’s a real chance some of what reaches your outlet started as steam under that same patch of ground.
Flash steam plants tap fluid hotter than 182°C, or 360°F, a common setup for many geothermal plants. As that pressurized water rises toward the surface and hits lower pressure, part of it flashes into steam almost instantly. That steam spins the turbine, and the leftover liquid can be flashed a second time to pull out more energy before it goes back underground.
Binary plants let developers build where the resource isn’t scalding hot. The geothermal fluid never touches the turbine. Instead it passes through a heat exchanger and heats a second fluid with a much lower boiling point, often a hydrocarbon like isobutane, which vaporizes from that modest heat and drives the turbine on its own loop. That’s a different technology from a geothermal heat pump, which uses the same stable underground temperature to heat and cool a single home instead of generating electricity.
| Plant type | Resource temperature | How it drives the turbine |
|---|---|---|
| Dry steam | Steam already dominant underground | Steam piped directly to the turbine |
| Flash steam | Above 182°C (360°F) | Pressurized fluid flashes to steam at the surface |
| Binary cycle | Below 182°C (360°F) | Heat exchanger boils a separate low-boiling-point fluid |
Source: U.S. Department of Energy, Geothermal electricity generation
Where the world’s geothermal capacity actually sits
Geothermal plants worldwide averaged a capacity factor over 75% in 2023, against under 30% for wind and under 15% for solar, per the same IEA report. Capacity concentrates in a handful of countries with active volcanic or rift zones, and the table below shows the top producers by installed capacity, together holding more than 93% of the roughly 17,173 MW installed worldwide.
| Rank | Country | Capacity, year-end 2025 (MW) |
|---|---|---|
| 1 | United States | 3,953 |
| 2 | Indonesia | 2,742 |
| 3 | Philippines | 2,034 |
| 4 | Türkiye | 1,797 |
| 5 | New Zealand | 1,259 |
| 6 | Kenya | 980 |
| 7 | Mexico | 976 |
| 8 | Italy | 916 |
| 9 | Iceland | 808 |
| 10 | Japan | 607 |
Source: ThinkGeoEnergy, Global top 10 geothermal power countries at year-end 2025. Türkiye’s total makes it Europe’s largest geothermal producer.
A capacity ranking doesn’t say how much of a country’s own power comes from geothermal. Kenya gets a higher share of its electricity from geothermal than any country, about 43% in 2022, because the Rift Valley gives it an unusually productive resource relative to the size of its grid. Indonesia produced more geothermal electricity than any other country that same year, about 17 billion kilowatt-hours, yet that made up 5% of its total electricity generation because its overall power demand is so much larger.
If you live in California, only about 5.2% of your electricity comes from geothermal, per 2022 EIA data, even though the state produces 68.6% of the country’s geothermal electricity, with Nevada providing most of the rest, at 24.7%.
What makes enhanced geothermal different
Every plant above depends on a natural hydrothermal reservoir, water-bearing rock with enough permeability for water to circulate on its own. Most of the planet’s stored heat isn’t packaged that way. Enhanced geothermal systems, or EGS, target hot rock that has the temperature but not the plumbing.
Engineers drill into that hot rock, then pump water down at pressure high enough to pry open or widen cracks already in the stone, the way water pressure can work loose a stuck jar lid. Once the rock can pass water again, crews circulate fluid between an injection well and a production well, pulling heated water back up to run a plant, usually a binary one.
If EGS works at scale, geothermal stops being limited to volcanic regions and becomes available almost anywhere a company can drill deep enough, whether that’s your state or one nowhere near a fault line. The IEA’s 2024 report put the potential at up to 800 GW of geothermal capacity worldwide, producing almost 6,000 terawatt-hours a year, matching current U.S. and Indian electricity demand combined. The same report projects EGS costs could fall 80% by 2035, to around $50 per megawatt-hour, a price that would put geothermal on your utility’s shopping list next to new gas plants.
In 2024, fewer than 30 countries had a geothermal-specific policy on the books, against more than 100 for wind and solar.
The Utah projects testing whether EGS scales
The clearest evidence that EGS has moved past the lab sits in Beaver County, Utah.
Fervo tested the concept in Nevada. Its Project Red pilot, drilled to about 7,700 feet deep with roughly 3,250-foot horizontal laterals, used the first horizontal well pair built for commercial geothermal, producing 3.5 MW before it wrapped up in 2023.
Cape Station, Fervo’s follow-on project near Milford, is a different scale. The company broke ground in September 2023 targeting an initial 400 MW, since upsized to 500 MW as new customers signed on. In September 2026, the project reached first power, the first utility-scale EGS project to do so anywhere in the world, according to Fervo.
The first phase, three 33 MW GeoBlocks, is now producing about 100 MW, and a second phase adding 400 MW more is under construction for 2028. Customers under contract for the roughly 900 MW total include Southern California Edison, which signed for 320 MW in June 2024, so if you get your power from SCE, some of your electricity could soon be coming from wells in Beaver County. Shell Energy North America signed a 31 MW deal in 2025. Google added the largest single piece in September 2026, committing to 396 MW to help power a planned data center in the state.
Fervo’s test on one well hit a flow rate of 107 kilograms per second at temperatures above 428°F, enough to support more than 10 MW of generation from that single well, which Fervo says beats what the National Renewable Energy Laboratory had projected the industry would reach before 2035.
A few miles away sits Utah FORGE, the Department of Energy’s EGS test site run by the University of Utah, built so researchers can test stimulation and monitoring with no revenue on the line. In September 2024, FORGE completed extended circulation tests showing good connectivity between its wells and temperatures around 370°F, and the DOE renewed its funding through 2028, adding $80 million.
Drilling has gotten measurably cheaper along the way. A 2025 Stanford Geothermal Workshop study by researchers Akindipe and Witter found well costs down 12% to 24% for vertical wells versus a 2017 baseline. Horizontal wells improved even more, down 18% to 26% over the same period. Most of the savings come from borrowing oil-and-gas hardware like diamond drill bits and pad drilling that spreads fixed costs across several wells.
Drilling costs, earthquakes and permits still slow EGS down
None of that means EGS will get solar-cheap fast. A November 2025 CleanTechnica analysis found EGS can’t repeat the cost collapse solar and batteries went through, since directional drilling and hydraulic stimulation are already mature, decades-old technologies with little room left for a learning curve.
Solar panels and batteries have roughly doubled their cumulative output every one or two years, while a single EGS project takes four and a half to seven years from first drilling to commercial power. That leaves room for only two or three doublings in that span. Oil and gas has drilled millions of wells over the past century. EGS might drill a few thousand wells globally before it counts as a mature industry, a volume CleanTechnica calls a rounding error next to oil and gas’s record.
EGS projects reported in late 2025 run $10,000 to $15,000 per kilowatt of capacity, against roughly $1,000 per kilowatt for utility solar. Even a 40% cost cut over the next couple of decades would leave EGS at $6,000 to $9,000 per kilowatt, still far above where solar sits now, so it won’t show up as savings on your power bill anytime soon.
Induced seismicity is the other hard limit, and it has already killed a project outright. The Basel, Switzerland EGS project began hydraulic stimulation in December 2006 and recorded 13,500 seismic events before it was over. Rising seismicity forced engineers to stop pumping after six days, and five hours after the well was shut in, a magnitude 3.4 quake hit, the strongest of the sequence. Geopower Basel eventually paid about 9 million Swiss francs in damage claims.
The project was permanently shut down in December 2009, three years after that quake spooked local authorities. That is why EGS developers now run real-time seismic monitoring with traffic-light protocols that slow drilling when shaking crosses a set threshold, and why regulators weigh a site’s distance from faults and population centers before permitting one.
Permitting on U.S. federal land has been the slower obstacle. The Bureau of Land Management oversees roughly 245 million acres with geothermal leasing authority, plus another 104 million acres under Forest Service jurisdiction. In April 2024, the BLM adopted categorical exclusions letting certain exploration work skip a full environmental assessment, though building the plant itself still triggers the standard review process.
EGS mostly repurposes oil and gas drilling tricks and points them at a different resource. What’s still open is whether enough wells can get drilled cheaply enough and safely enough to make EGS worth building outside a handful of well-funded projects. Fervo, the Department of Energy’s Utah FORGE researchers and the data center operators now signing long contracts for EGS power are the ones running that experiment. Cape Station’s next phase, already under construction for 2028, will be the next real test of the answer.